Asheville · Boone · Sylva
Mountains
Ice dams, heavy snow loads, falling hardwoods and, after Helene, wind-versus-flood questions on mountain homes and cabins.
Independent property claim appraisal · all 100 counties
When your insurer accepts the claim but the payment won’t rebuild what you lost, North Carolina Insurance Appraiser prepares an independent, line-by-line valuation and takes it through the appraisal process written into your policy.
What we do
Most underpaid claims in this state aren’t denied. They’re short: a slope left off the roof, a hardwood floor that stops at the doorway, an ice-storm limb strike priced as a patch, code work nobody included. North Carolina Insurance Appraiser exists for the gap between “covered” and “paid in full.”
When either side invokes the appraisal clause, you name an appraiser, the carrier names one, and the two of them (with an umpire if needed) set the amount of loss. As your North Carolina Insurance Appraiser, we build the number you take to that table and we defend it item by item.
Services
From a quick estimate audit to full appraisal panel representation and neutral umpire work, each service is built around a valuation that holds up.
Storm record
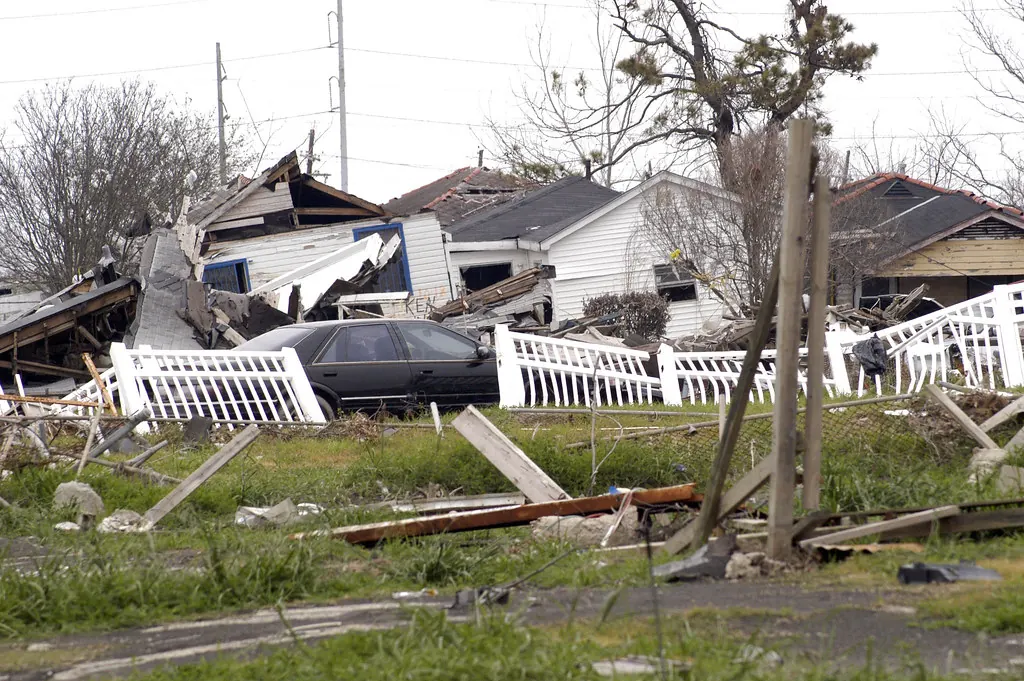
A North Carolina Insurance Appraiser has to understand what each kind of event does to a building. These are the storms property owners here still measure against.
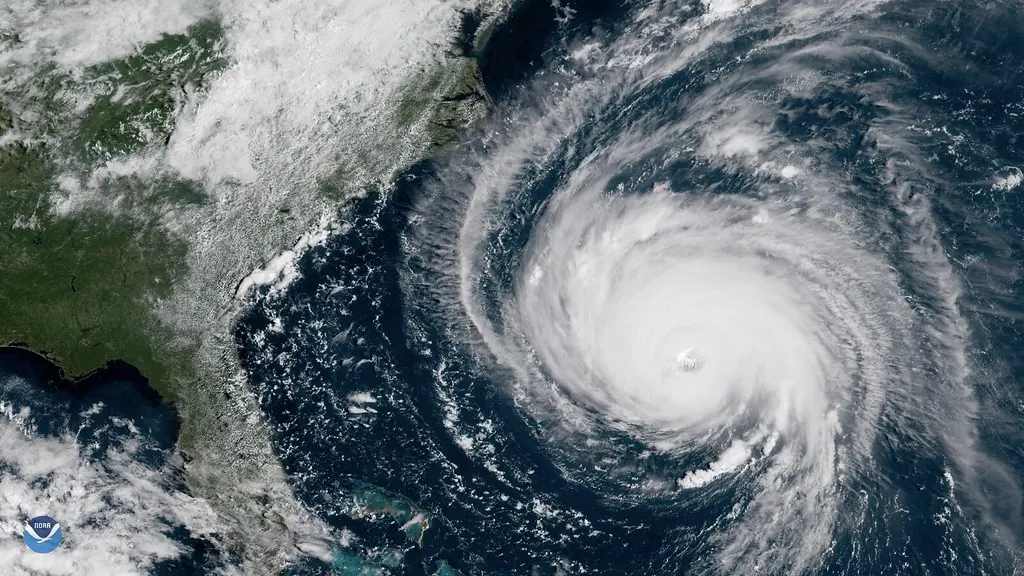
Came ashore near the state line as a major hurricane; its surge flattened much of the southern Brunswick County beachfront.
Stayed strong far inland and brought down trees across Charlotte and the western Piedmont.
Landed near Cape Fear and carried damaging wind and falling trees deep into the Triangle.
Produced record river flooding across eastern North Carolina, including the Tar and Neuse basins.
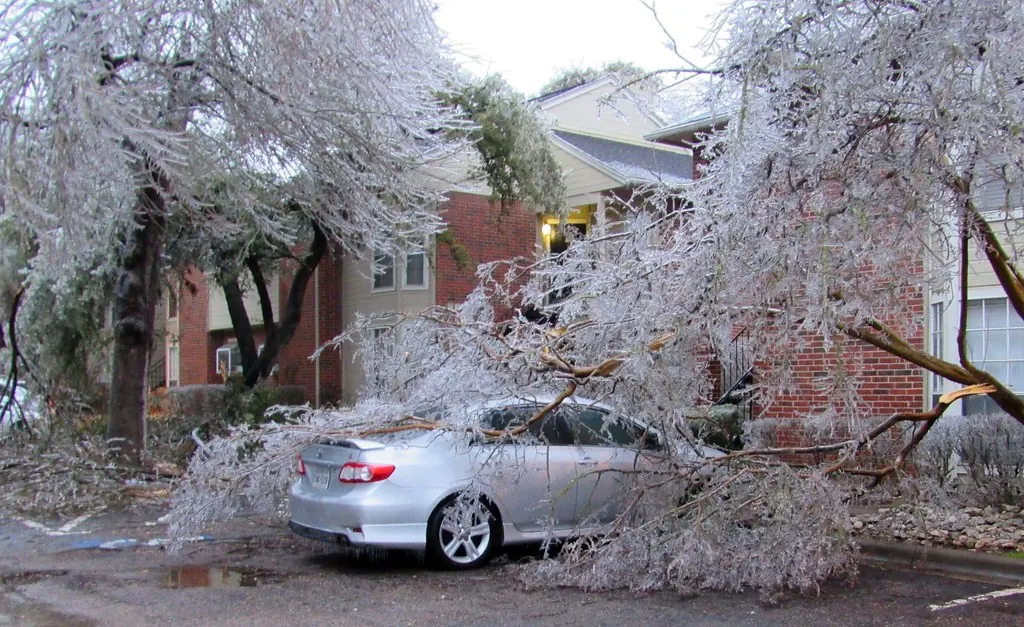
Freezing rain coated the Piedmont from Charlotte to Raleigh and left well over a million customers in the dark.
An outbreak of tornadoes crossed central and eastern counties, striking Sanford and parts of Raleigh.
Drove severe river flooding along the Lumber, Neuse and Cape Fear basins.
Made landfall near Wrightsville Beach, stalled, and pushed surge up the Neuse into New Bern.
Caused catastrophic flooding, landslides and wind damage across the western mountains.
Swipe or scroll sideways to see the full timeline.
Six claim climates
Our state stretches more than 500 miles. A North Carolina Insurance Appraiser working in Boone faces different losses than one working in Nags Head, and the estimate has to reflect that.
Ice dams, heavy snow loads, falling hardwoods and, after Helene, wind-versus-flood questions on mountain homes and cabins.
Strong thunderstorms, hail and ice storms where the Piedmont meets the Blue Ridge escarpment.
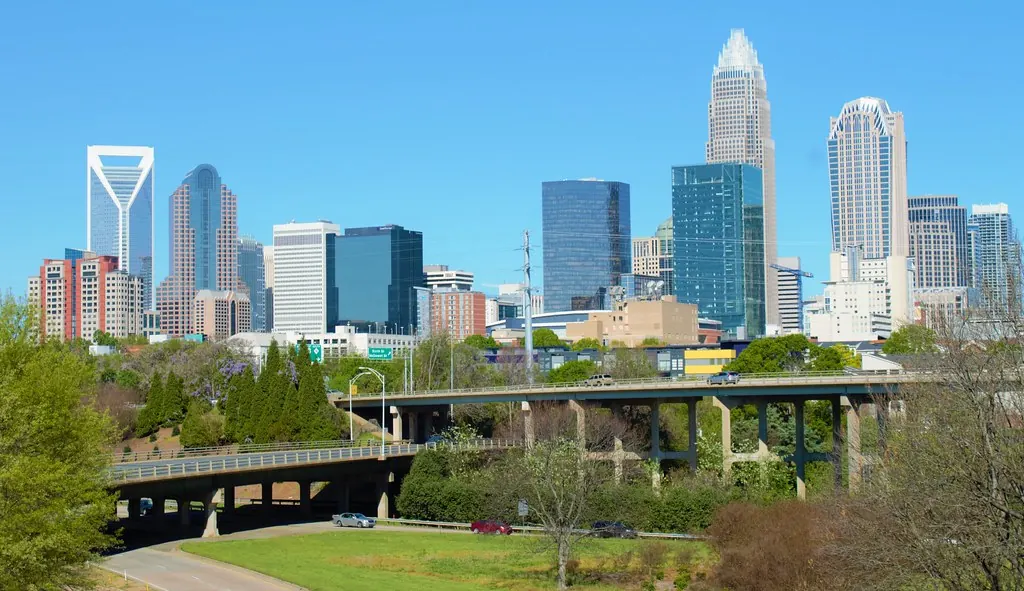
The state’s hail and ice-storm belt, with dense tree canopy over older neighborhoods and fast-growing HOA suburbs.
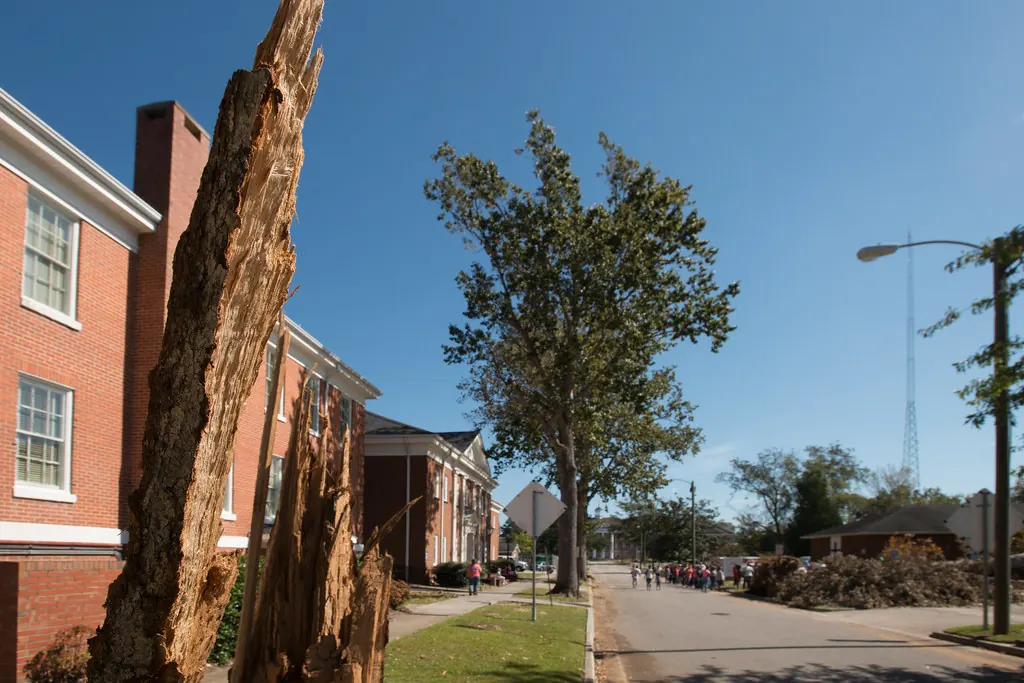
Tornadoes, tropical remnants and long-leaf pines that snap in high wind, plus large rental and military housing stocks.
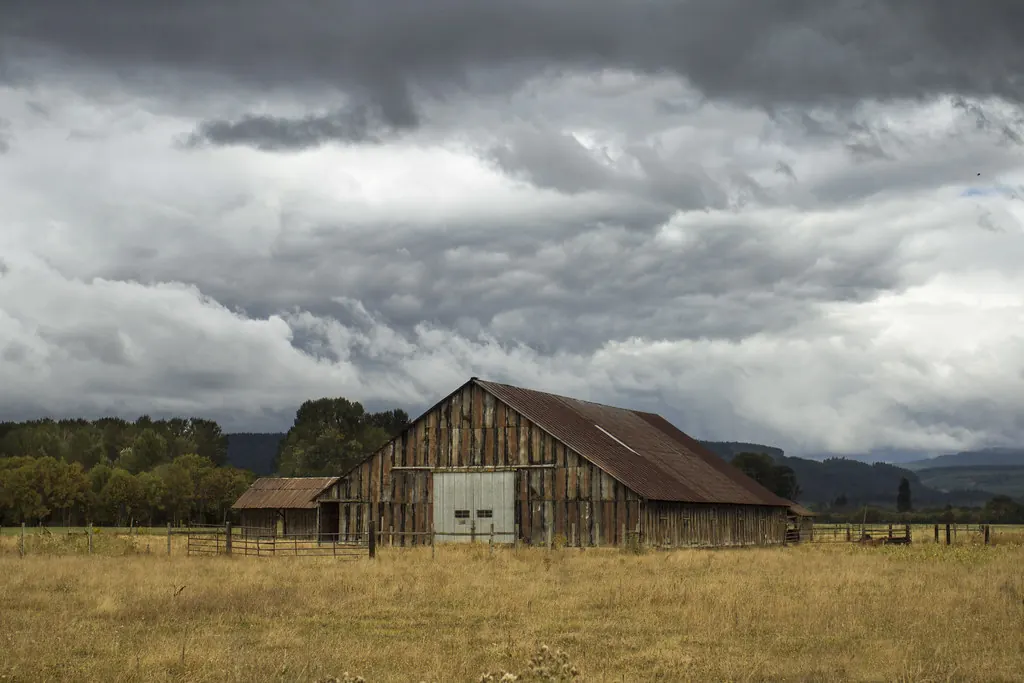
River flooding from slow hurricanes, farm structures and older homes on crawlspaces.
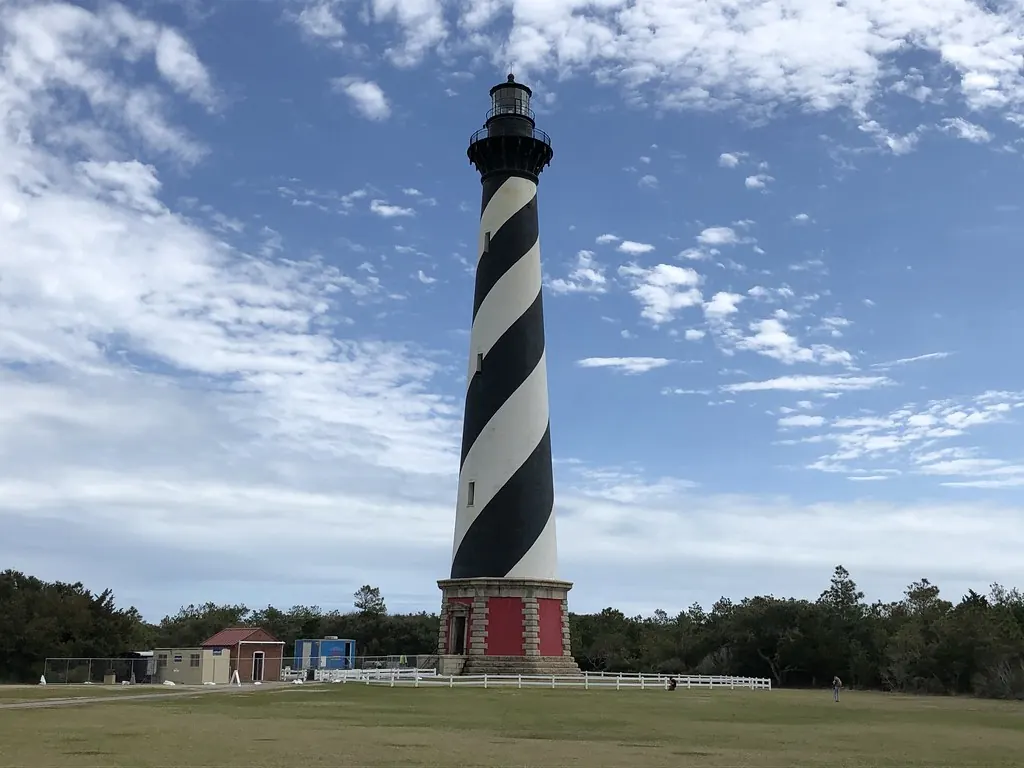
Named-storm deductibles, coastal pool policies, wind-driven rain and homes on pilings.
The process
The appraisal clause turns an open-ended argument into a defined process with a binding answer on the amount of loss.
Send the policy, the carrier’s estimate and your photos. A North Carolina Insurance Appraiser reads them and tells you plainly whether appraisal fits.
We inspect, measure and photograph the property, then build a line-item estimate priced for your area.
Appraisal is demanded in writing and we’re named as your appraiser within the policy’s deadline.
We work line by line with the carrier’s appraiser. Most disputes narrow sharply here.
Open items go to a neutral umpire; two signatures set the amount of loss and payment follows.
Quick check
Type in the two numbers you already have. A large gap is worth a conversation with a North Carolina Insurance Appraiser; a small one may close faster with a documented supplement request.
The full settlement gap estimator adds appraiser and umpire fees and shows your net at three outcomes. All figures are illustrative.
Free calculators
Check the carrier’s math before you pick up the phone. Every calculator runs in your browser; nothing is stored or sent.
All calculators Estimator
 CalculatorEstimator
 CalculatorPlanner
 Checkup
 Worksheet
Areas we serve
We take claims in every county. These twelve local pages cover the places we’re called to most.
Choosing help
Each solves a different problem. A North Carolina Insurance Appraiser will point you elsewhere when appraisal isn’t the right tool.
Questions
Straight answers on how appraisal works, what it costs and when it’s the wrong move.
We value property damage when you and your insurer agree the loss is covered but disagree on what it costs. As your appointed appraiser we inspect, write an independent line-item estimate, work with the carrier’s appraiser and, if needed, present open items to a neutral umpire.
No. A public adjuster handles and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question, the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
When coverage has been accepted, you have the carrier’s estimate, and the gap between it and a qualified contractor’s estimate is meaningful, often more than about 10% or several thousand dollars.
On the amount of loss, generally yes, once two of the three panel members sign. Coverage questions are not decided by the award.
Each side pays its own appraiser and usually half of the umpire. We put our fee terms in writing before any work begins, and the first conversation is free.
Yes. We work in all 100 North Carolina counties, from the mountains to the Outer Banks, with frequent work around Charlotte, the Triad, the Triangle, Fayetteville, Wilmington and the coast.
Guides
Practical guides from North Carolina Insurance Appraiser on policy language, documentation and strategy.
What a written appraisal demand should include, the timelines common in North Carolina policy forms, and the mistakes that slow the process down.
After a hurricane, the line between wind and water decides which policy pays. Here is how that line gets drawn, documented and, sometimes, appraised.
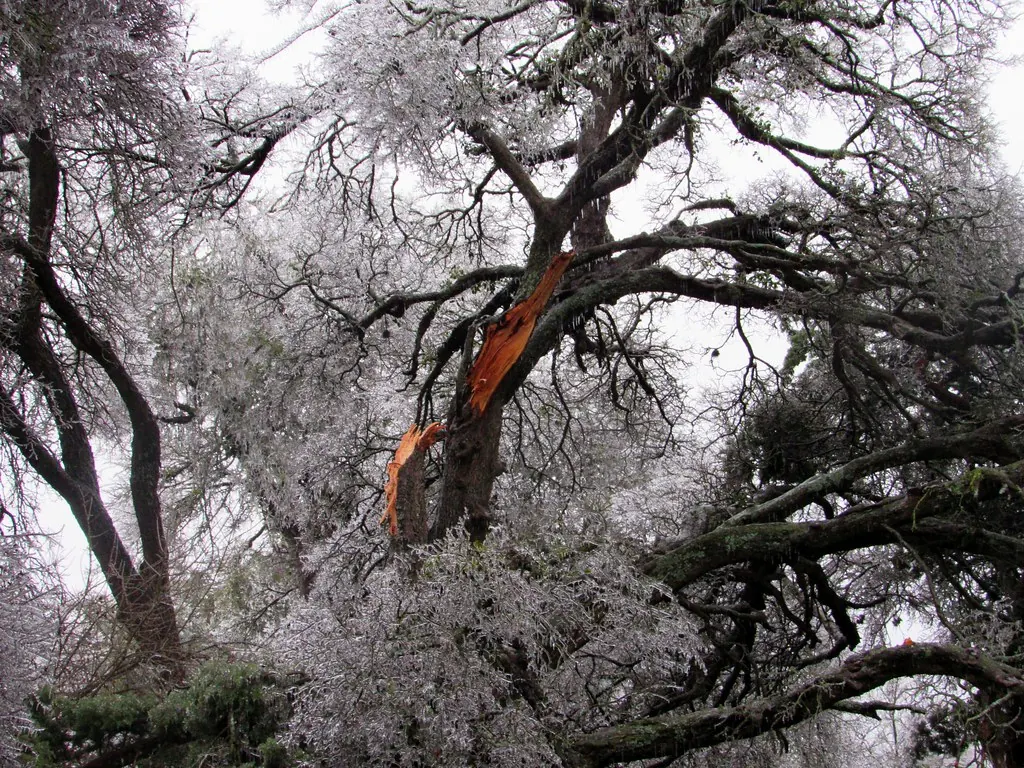
Falling limbs, burst pipes and ice dams each raise different claim questions. How to protect the property, document the loss and handle estimate disputes.
Before you sign the release
A short review now can keep you from accepting a settlement that won’t cover the repair.
Start here
Tell us what happened and what the carrier offered. You’ll get a straight answer on whether appraisal is worth pursuing, with no pressure.


